Social and spiritual capital

When we talk about building wealth, we almost exclusively talk about money. We track our investment returns, our property values, and our retirement accounts. We measure our success by the size of our balance sheets.

But perhaps true wealth cannot be measured by a single metric. We could potentially consider three distinct types of capital: financial, social, and spiritual.

Financial capital is the easiest to understand. It is the math. It is the money that funds our lives. But it doesn’t exist in isolation.

But the other two are where our actual lives happen. This is where the money is used as a tool.

Social capital is the strength of our relationships. It is the time spent with our family, our deep friendships, and our connection to a broader community.

Spiritual capital is our sense of purpose. It doesn’t necessarily mean religion. It is our core values, our deepest beliefs, and the “why” that gives our lives meaning and direction.

Here is the trap we so often fall into.

We often spend the first half of our lives aggressively pursuing financial capital. We work long hours, tolerate immense stress, and sacrifice our weekends. We do this hoping that one day, the money will buy us the time to finally focus on our relationships and our purpose.

If we’re not careful, we might deplete our social and spiritual capital to fund our financial capital.

A massive financial portfolio is incredibly hollow if we have alienated the people we wanted to share it with. And absolute financial freedom is deeply disorienting if we have no underlying sense of purpose to guide our days.

Financial capital is simply a tool. It has absolutely no inherent value on its own.

Its only real job is to protect, nurture, and expand social and spiritual capital. As our previous blog stated from Mitch Anthony, money is a tool to fund, not find, our purpose.

Before we look at the spreadsheets or the tax structures, we have to define what actually matters. Who are the people you want to spend your time with? What is the purpose you want to pursue?

When we are able to establish our social and spiritual capital, the math gains a clear mandate. We stop accumulating money just for the sake of it. We start intentionally structuring our wealth to serve the people and the principles we care about most.

Because true security isn’t just having a fully funded portfolio. It is knowing exactly who you are sharing it with, and why it matters.
Long-term plans need short-term protection

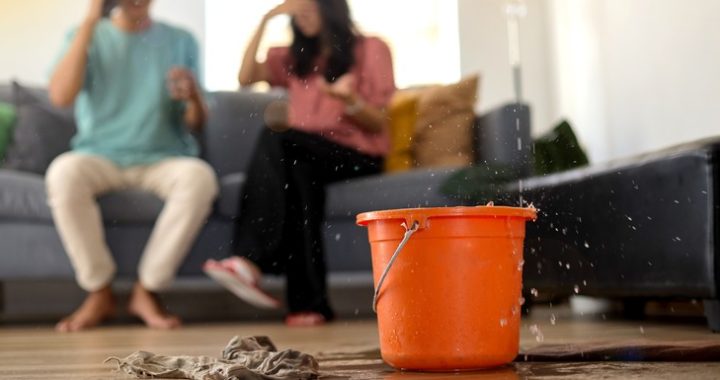
Imagine you have been diligently saving for a milestone family holiday. You have carved out the time, set aside the capital, and prioritised your “Return on Memories.” But out of nowhere, a severe storm damages your roof, or a burst geyser floods your kitchen.

It’s not nice to think about, but… it could happen.

When we talk about financial planning, we often expect to focus on the the big things. You prepare to discuss goal timelines, investment portfolios, and the legacy you want to leave behind.

You probably don’t expect them to ask about your car insurance or your household cover. This is especially true if your planner doesn’t even offer those specific products. Why would they care about your household policy if that’s not their focus?

Because a good financial plan is a carefully balanced, interconnected ecosystem.

If your short-term insurance is inadequate, or if you decided to self-insure to save on monthly premiums, that event becomes the first falling domino.

To cover the massive repair bill, you are forced to raid your emergency fund. If that isn’t enough, you might have to liquidate long-term investments, potentially triggering unexpected tax consequences or selling during a market dip.

Suddenly, the cash flow meant for the family holiday has to be redirected to pay the plumber. The true cost of the event wasn’t just the price of a new geyser and pipe system. The true cost was the disruption of your long-term trajectory. It was the family memory you didn’t get to make.

A great financial planner doesn’t need to sell you a short-term policy to care deeply that you have a good one.

They care because they are the architect of your master blueprint. They know that if the foundation is left completely exposed to everyday risks, the entire structure becomes incredibly fragile.

Short-term insurance can act as a defensive moat around your life’s work.

It acts as a circuit breaker, stopping the dominoes from knocking into your long-term wealth. It ensures that a random Tuesday emergency doesn’t force you to cannibalise your future to pay for the present.

We don’t focus on the “boring” details like household cover because we love paperwork.

We insist on getting those details right because it is the only way to ensure your capital remains focused on its true job: funding a vibrant, flourishing life, no matter what curveballs come your way.

The new retirementality

For decades, many of us have been sold a very specific version of retirement. We are culturally conditioned to believe that at a certain age, we should step away from our careers, retreat from the world, and live out a permanent, quiet holiday.

But as medical treatment improves and lifestyles become more intentional, this traditional model is starting to feel less and less relevant.

A pioneer of lifestyle financial planning, Mitch Anthony, has spent years redefining how we approach this massive life transition. In his work on The New Retirementality, he outlines a better, more human-centric framework.

If you want a retirement that truly flourishes, he believes that it comes down to four fundamental shifts in mindset.

  1. Engage at any age

Society loves to assign us a financial expiration date. But you should never let “them” tell you when you are done. If you love your work, or if it brings you deep joy and mental stimulation, there is absolutely no rule that says you must stop at sixty-five. You have earned the right to define your own timeline.

  1. Retire “to” something, not “from” something

Many people view retirement as an escape hatch. They are exhausted, and they simply want to exit the stress of a demanding career. But running from something is not a long-term life plan. If you don’t have a clear, exciting vision of what you are retiring to, the sudden quiet can be incredibly disorienting.

  1. Find the balance between vacation and vocation

We all need to rest and recover. But a thirty-year vacation eventually loses its shine. Human beings are fundamentally wired to be useful. A flourishing second act finds the perfect rhythm between pure leisure (vacation) and meaningful, chosen work (vocation).

  1. Purpose matters just as much as capital

As Mitch Anthony so perfectly states, money can help you fund a purpose, but it cannot help you find a purpose. We often mistakenly believe that hitting our financial target will automatically grant us a sense of direction. But the greatest portfolio in the world is ultimately useless if it isn’t attached to a meaningful life.

This is the true value of integrated lifestyle financial planning.

Our goal is never just to engineer the math so you can afford to stop working.

Our role is to act as your thinking partner, helping you intentionally design a vibrant, engaged next chapter. Because true wealth isn’t just about how much capital you have accumulated. It is about how well you actually live.

The freedom of an open hand

When there are bills to pay, and income feels like it’s not quite enough to cover the monthly expenses, it’s easy to hold back on generosity. Sometimes, we might even treat generosity as a financial finish line.

We tell ourselves that once we hit a certain net worth, or once we finally retire, then we will start giving back. We want to ensure our own bucket is completely full before we are in a position to share.

It is a perfectly logical way to think. But it carries a hidden behavioural risk.

If we spend our entire working lives fiercely guarding every single cent, accumulation becomes our default setting. We wire our brains for scarcity. When we finally reach our financial goals, we often find that the clenched fist is incredibly hard to open.

There’s a principle in financial planning that encourages a very different approach. It views generosity not as a distant destination, but as a habit to cultivate along the journey, creating the opportunity to experience freedom today, not just “some day”.

You do not need to be independently wealthy to be a steward of your money.

Stewardship is simply the everyday realisation that wealth is a tool meant to be used, not just a number to be hoarded.

When we integrate giving into our current financial plan, even in small, structured ways, it radically changes our relationship with our financial capital. It actively breaks the anxiety of scarcity. It reminds us, in real-time, that we actually have enough to share today.

Studies on human flourishing consistently show that helping others is one of the most powerful drivers of a meaningful life. Why would we delay experiencing that joy until the very end of our careers?

A good financial planner helps you build this into your blueprint right now.

We help you balance your long-term security with your present-day values. We can mathematically plan to help you save for your future while still making a tangible impact today.

Generosity adds a profound layer of meaning to the daily grind. It transforms our money from a source of background stress into a dynamic source of human connection.

The greatest return on our investment isn’t found in waiting for a “someday” that might never arrive. It is found in the lives we are able to touch along the way.

Creating a single view for your wealth

There is a common belief that when it comes to our wealth, we should never put all our eggs in one basket. It’s easy to extend this logic to our financial advice.

We often assume that having multiple advisers is the safest approach. We might have one for our retirement fund, one for our stock portfolio, and perhaps another for our tax structuring.

It feels like we are diversifying our risk and getting a healthy mix of second opinions. But in practice, this fragmented approach often creates a hidden, exhausting problem.

When your financial affairs are spread across multiple professionals, you inadvertently become the project manager of your own wealth. Because none of your advisers are talking to each other, no one holds the master blueprint.

One adviser might be taking an aggressive risk approach, while another is overly conservative, quietly cancelling out your overall strategy. There might be overlapping fees, hidden tax inefficiencies, or glaring blind spots in your estate plan.

It is like hiring a team of brilliant subcontractors to build a house, but never appointing a lead architect. They are all working hard, but no one is making sure the rooms actually connect.

You end up carrying the heavy cognitive load of holding the entire strategy together in your own head. Trusting a single, dedicated financial planner to manage your entire life’s work does require a leap of faith.

It requires you to be entirely vulnerable and completely transparent about your full financial picture. You have to lay all the cards on the table.

But the reward for that transparency is profound clarity!

When one planner sees the entire board, the conversation completely changes. They are no longer just managing a specific bucket of money; they are managing the complete architecture of your financial plan.

A holistic, integrated planner understands how your tax strategy impacts your estate, and how your monthly cash flow funds your family holidays.

They know exactly when you plan to transition into your “second act,” and can align every single asset to support that specific transition. Because they have the full picture, they can proactively spot risks that a siloed adviser would simply never see.

True lifestyle financial planning cannot happen in a vacuum.

It requires a deep, ongoing partnership with someone who understands your entire history and your ultimate values.

This certainly doesn’t mean there is no place for deep specialists. When it comes to complex tax, legal, or business structuring, specialized expertise is absolutely invaluable.

But those specialists do their best work when guided by a central plan.

Instead of a collection of fragmented opinions, you need one objective thinking partner who holds the master blueprint. You need someone who can coordinate the experts, ensuring every piece of advice pulls in the same direction, and aligns perfectly with what your wealth is actually for.

The invisible scripts

Did you know that, according to cognitive scientists, the average person processes over 6,000 distinct thoughts every single day. That’s around six to ten thoughts per minute.

It is an overwhelming amount of mental data flowing through our minds from the moment we wake up. But have you ever paused to ask what is actually driving all of those thoughts?

When it comes to our money, we like to believe that our thought process is purely logical. We assume that when we review our portfolios, set our budgets, plan for a holiday, or conclude a business deal, we are acting as perfectly rational beings.

If personal finance were just about the math, it would be incredibly simple.

But money is rarely just about the numbers. It is deeply tangled in emotion, security, and our personal history. Behind those thousands of daily thoughts, our financial choices are being quietly directed by “invisible scripts.”

These are the deep-seated, subconscious beliefs about money that we picked up decades ago, often without even realising it. We absorbed them from watching our parents navigate financial stress, from our own early career struggles, or from the relentless culture around us.

Perhaps your internal script says, “I must constantly hustle and produce to be considered worthy.” Or maybe it whispers, “Spending money on myself is irresponsible,” or, “I have to keep up with my peers to prove I am successful.”

Because these scripts are invisible, they run our daily choices completely unchecked. They dictate how much we save, the amount of investment risk we are willing to tolerate, and whether we ever allow ourselves to actually enjoy the fruits of our labour.

But here is the inherent danger of an unexamined script. If left in the dark, these hidden beliefs can slowly ruin our peace of mind.

They can turn a perfectly funded retirement into a source of constant anxiety. They can cause us to hoard capital long past the point of necessity, preventing us from spending our wealth on the experiences and people we love.

We can have a flawless balance sheet, but still feel entirely trapped by our own psychology. This is why financial planning has to go beyond the spreadsheet.

A great financial planner doesn’t just look at the math; they act as an objective mirror. They help you uncover the invisible scripts that are quietly running your life.

When we finally drag these hidden beliefs into the light, they lose their power.

By identifying and rewriting these outdated scripts, we take back control. We ensure that our past is no longer dictating our future, and that our wealth is finally free to serve our true values.

The value of a financial thinking partner

When we think about working with a financial planner, we often assume the value lies entirely in the numbers or the brokering of a financial product or contract. We naturally expect them to pick the right investments, optimise our tax, and help us generate a better yield.

Those technical elements are certainly important.

But true lifestyle financial planning goes far beyond the spreadsheet. The real value is rarely found in simply trying to beat the market. It is found in the deeply human support that helps us build a flourishing life.

When you engage with a qualified and experienced financial planner, you are really bringing six specific pillars of value into your financial journey.

Bringing order to the chaos

As our lives grow more complex, our finances often become fragmented. A planner helps bring profound order (and simplicity!) to your financial world. We sort through the macro elements, like investments and estate planning, while also helping you make sense of the micro, like your monthly cash flow. Slowly, clarity replaces confusion.

Following through on our intentions

We all have great intentions for our money. But life gets busy, and it is incredibly easy to lose focus. A planner provides gentle and consistent accountability. They help us prioritise our goals, map out the required steps, and regularly review our progress so we actually follow through on our commitments.

An objective sounding board

Because money is tied to our sense of security, it is deeply emotional. When the markets dip, our instinct is to panic. A planner provides a calm, objective, outside perspective. They ensure we have factual context before making major moves, protecting us from emotionally driven decisions.

Anticipating the seasons of change

Life doesn’t happen in a straight line. We transition through careers, into retirement, and sometimes face unexpected family emergencies. A proactive planner anticipates these major transitions long before they happen, building robust action plans so that you are never caught off guard.

Cutting through the complexity

The financial world is filled with intimidating jargon. A good planner doesn’t try to impress with complex terms; they act as an engaged educator who wants to connect, not simply correct. We can help you break down complicated financial choices into simple concepts, empowering you and your family to make confident, informed decisions about your own wealth.

A true partnership

Finally, lifestyle financial planning is never just a transaction. It is a deep, ongoing partnership. Your planner works with you, not just for you. They take the time to understand our history, our values, and our family dynamics.

Ultimately, the goal is never just to grow a pile of money. It is to partner together, using these six principles to help us achieve the absolute best life possible with the wealth we have.

The real purpose of short-term insurance

It is perhaps the ultimate grudge purchase.

Every single month, we watch the premium leave our bank accounts. We pay to insure our cars, our homes, and our household contents, often wondering if it is simply money down the drain.

Because if we have a quiet year with no claims, it can easily feel like a wasted expense.

But if we look at it through the lens of our overall financial wellbeing, it might be helpful to fundamentally reframe why we actually buy short-term insurance. We naturally assume we are just paying to replace a damaged bumper, fix a burst geyser, or replace a stolen laptop.

But that is only the mechanical side of the transaction. What we are actually buying is emotional margin. Life is inherently unpredictable, and things will inevitably break, crash, or go wrong. When these moments happen, they bring a sudden, heavy wave of stress and cognitive overload.

If we don’t have adequate cover in place, we are forced to deal with two massive problems at exactly the same time.

We have to navigate the logistical nightmare of the emergency, and we have to absorb the sudden financial trauma. We suddenly have to raid our emergency funds, or pull money from our investments. We are forced to disrupt the capital we were patiently building for our family’s future, just to fix a problem in the present.

Proper short-term insurance isolates the friction.

It takes a deeply stressful, unpredictable event and downgrades it from a financial crisis to a mere logistical inconvenience. It allows us to stand in the middle of a frustrating situation and confidently say, “This is incredibly annoying, but we are going to be okay.”

We don’t have to panic about where the funds will come from. We don’t have to sacrifice our long-term goals to pay for a short-term accident. We want our capital to fund our purpose, our healthspan, and our shared family experiences.

Every time we have to self-fund an unexpected disaster, we drain the precious resources meant for those higher purposes. In this way, short-term insurance acts as the defensive wall around our life’s work.

It is the quiet guardian of our peace of mind.

So, the next time that monthly premium goes off, it might be helpful to view it a little differently. We aren’t just protecting our physical possessions. We are actively protecting our mental and emotional bandwidth, ensuring that one bad day doesn’t derail our long-term journey.

Am I going to be okay?

Am I going to be okay? This is one of the most commonly asked questions. Research in financial therapy shows that we don’t buy products; we buy peace of mind. Underneath every question about fee structures or historical returns, we are actually asking a much simpler, deeply human question: ‘Am I going to be okay?’

It is the quiet worry that can so often keep us awake at night.

We wonder if we have saved enough, if the market will hold, or if an unexpected life event will suddenly derail our carefully laid plans. In our search for an answer, we naturally look to our bank balances for reassurance.

We assume that if we can just accumulate a little bit more, if we can just hit that magic retirement number, the anxiety will finally disappear. We believe that security is found at the bottom of a spreadsheet.

But there is a gentle, yet profound truth we often miss along the way. A large pile of money, on its own, does not actually create peace of mind.

Without a clear blueprint, capital is just potential. It is like having a massive pile of bricks sitting in an empty field. The bricks themselves don’t provide shelter or warmth. It is the architectural plan, the intentional design of the house, that actually keeps the rain out and creates a space that feels like a home.

True financial security is not found simply in having money. It is found in having a plan to use it wisely. When we shift our focus from just accumulating wealth to actively designing our lives, everything changes.

We stop asking if we have “enough” in a vacuum, and start asking what we actually want our money to do.

When we try to hold all our financial variables in our heads, the cognitive load is exhausting. We carry the heavy weight of inflation, market volatility, and future healthcare costs squarely on our own shoulders.

But a good lifestyle financial plan allows us to offload that burden.

It maps out our future cash flows, stress-tests our assumptions, and builds a defensive wall against the unexpected. It gives every single bit of our capital a clear job to do. More importantly, it provides us with a framework for making decisions when life inevitably changes. When the markets dip, or when our personal circumstances shift, we don’t have to panic. We simply return to the blueprint. We adjust the strategy, knowing that the foundation is secure.

Answering the question, “Am I going to be okay?” isn’t about perfectly predicting the future or hoarding endless capital.

It is about knowing that we have a robust, flexible strategy in place. It is the quiet confidence that comes from moving our trust away from the unpredictable markets, and placing it firmly in our intentional plan.

What’s running the show?

We invent tools to make our lives easier, more efficient, and more comfortable. But there is a strange phenomenon that happens when we aren’t paying attention. Sometimes, the tool quietly becomes the master.

Money is perhaps the greatest example of this.

At its core, wealth is simply a utility. It is meant to be a tool that we use to build a flourishing, meaningful life.

But without strict boundaries, it is incredibly easy to let the pursuit of that wealth completely run our lives. We often allow it to dictate our daily schedules and our underlying stress levels. It decides how many hours we work, how often we check our emails at the dinner table, and how much mental energy we have left at the end of the day.

We tell ourselves we are just doing what it takes to be responsible. We are simply providing for the people we love.

But there is a dangerous tipping point we have to watch out for. If we let this pursuit run unchecked for too long, it can eventually ruin the very things we are supposedly building the wealth to protect.

Perhaps, we can think of it like a vineyard.

A vine is ultimately designed to produce fruit. But if a vineyard is left completely unattended, allowed to just grow wildly in every direction, it quickly becomes tangled and knotted. All of its energy goes into producing sprawling, heavy branches, and the vine eventually stops bearing actual fruit.

Our lives work the exact same way.

When we let our financial ambition and the pursuit of a bigger safety net grow wildly without intentional pruning, we become knotted by stress. We sacrifice our physical health and our cognitive vitality in the name of limitless accumulation.

We miss the quiet, unhurried moments with our children or our partners. We delay our shared experiences and our joy. The very thing that was supposed to buy our freedom ends up building a very comfortable prison.

Instead of running the show, it ruins the show.

So, how do we flip the dynamic? How do we put ourselves back in the driver’s seat?

It starts with a profoundly simple, yet difficult exercise. We have to define our “enough.”

This is the true heart of lifestyle financial planning. It is stepping back from the relentless cultural conditioning of “more” to ask what we actually need the money to do. It is the deliberate act of pruning the vine, ensuring our energy flows into the fruit rather than the branches.

When we define our personal finish lines, the endless treadmill finally stops.

We can look at our balance sheets and confidently say that the tool has done its job. We have enough to fund our healthspan, our relationships, and our sense of purpose.

Financial peace isn’t found when we finally accumulate enough capital to escape the world, but when we are empowered to leave the world better than we entered it. It is found in the quiet truth that our money is simply there to fund our lives, rather than running them.